Alternative Credit Scoring for Saudi Arabia’s Lending Market
Expand lending and control risk in Saudi Arabia with alternative credit data powered by 450+ applicant real-time signals.


Regional Saudi services
for digital footprint analysis
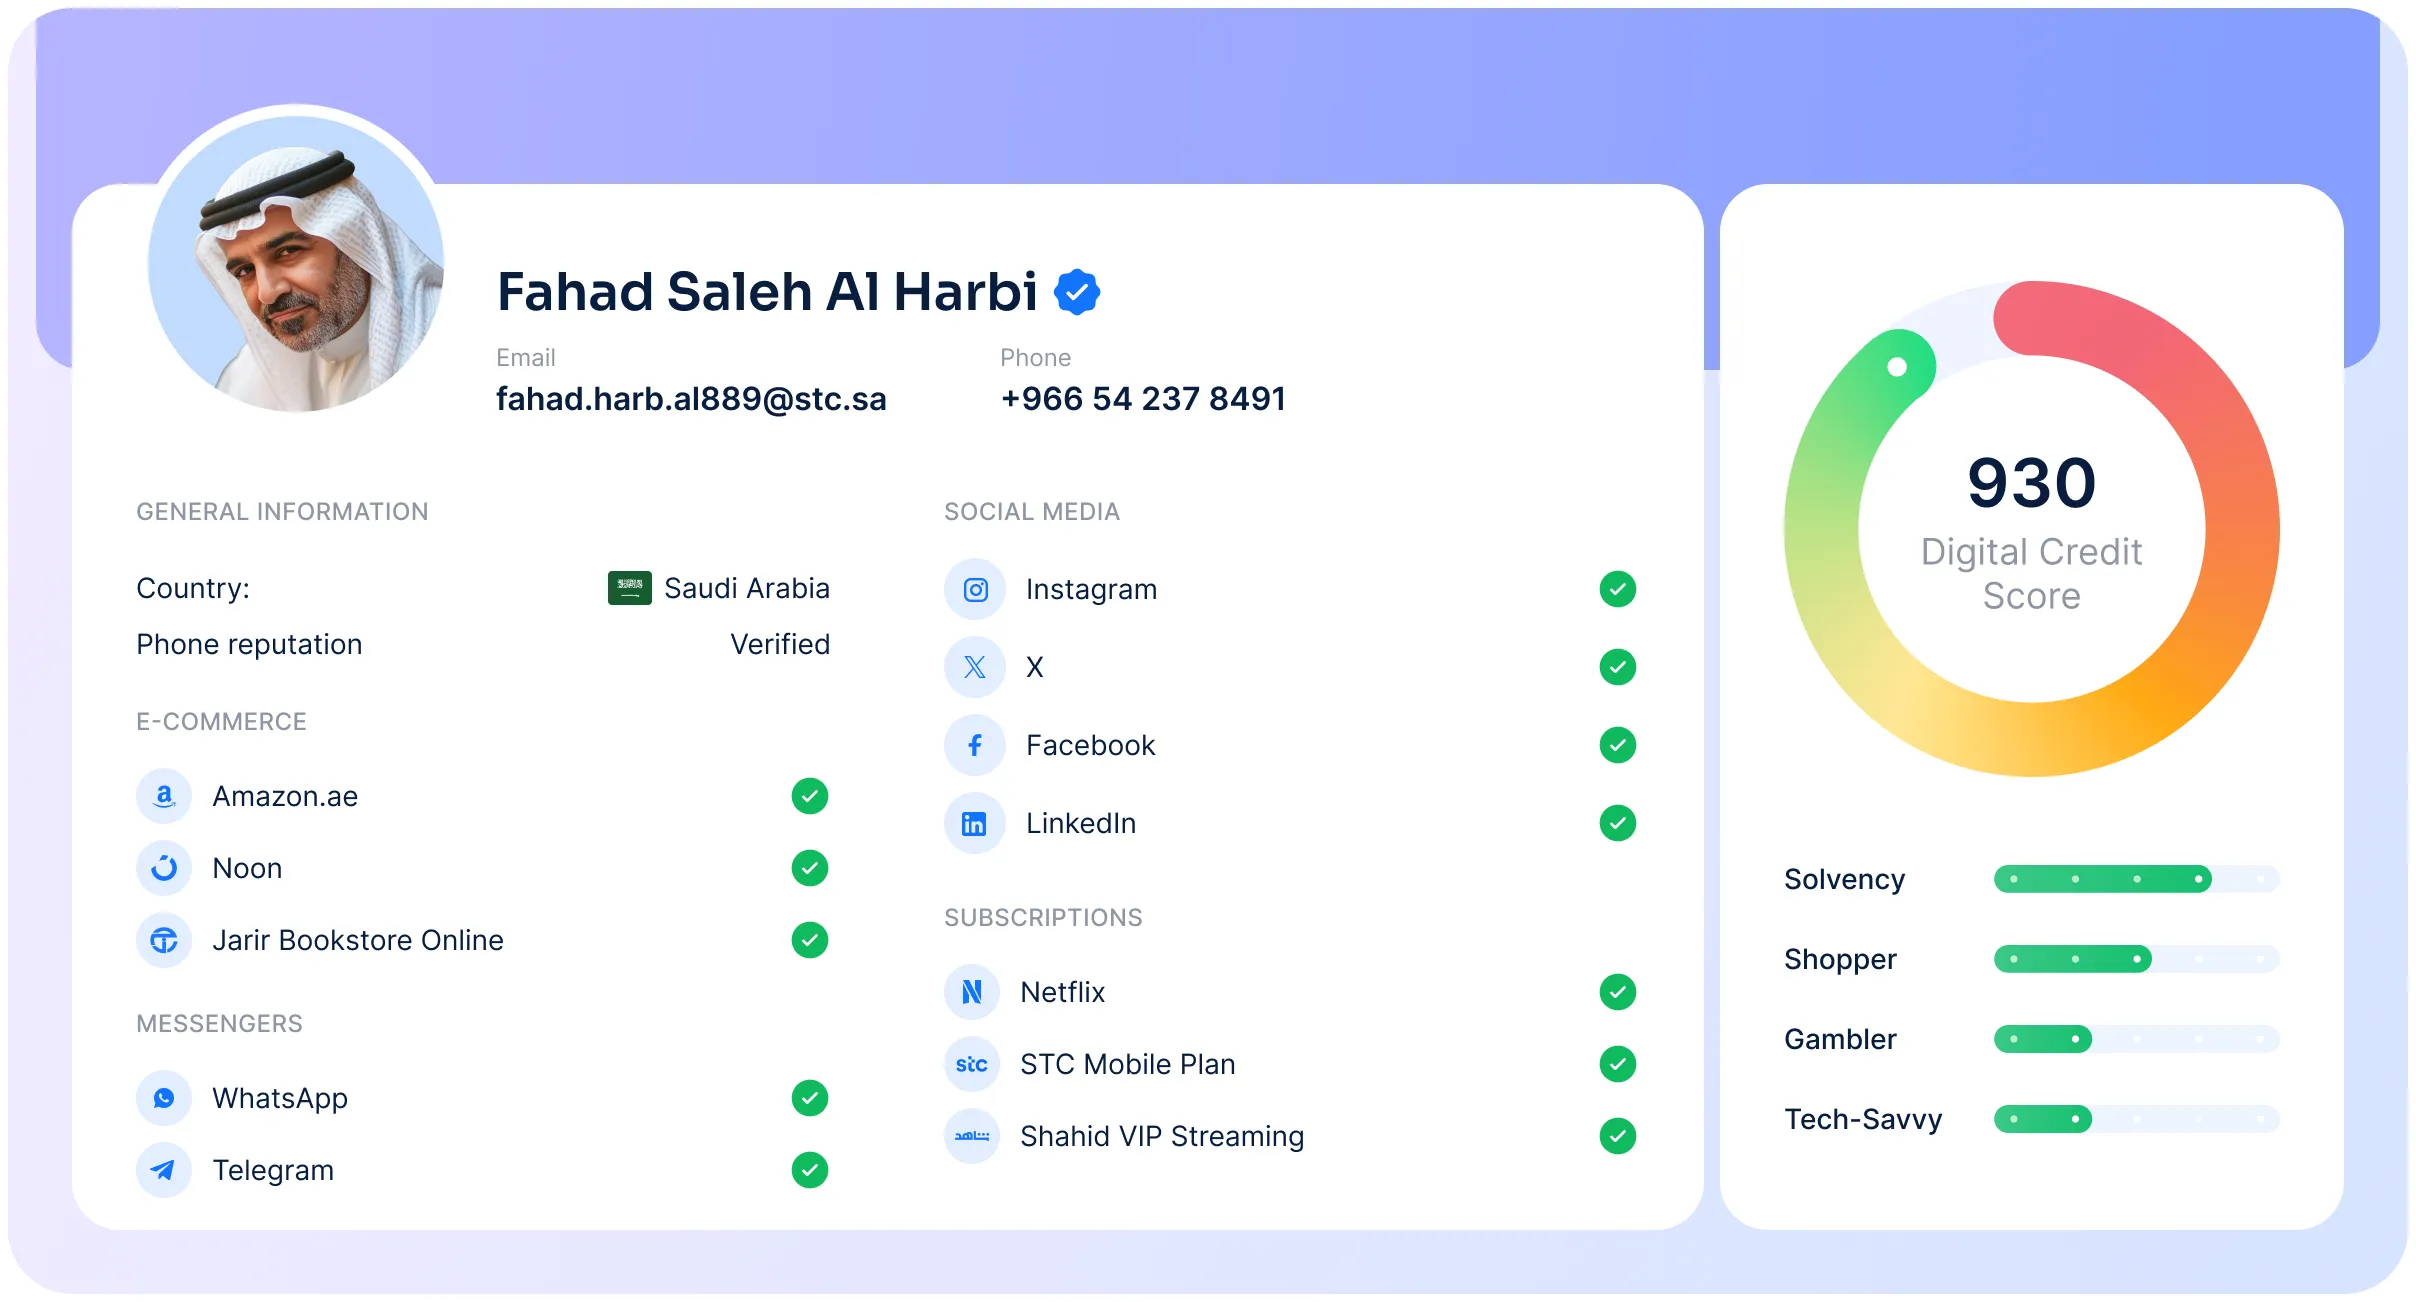
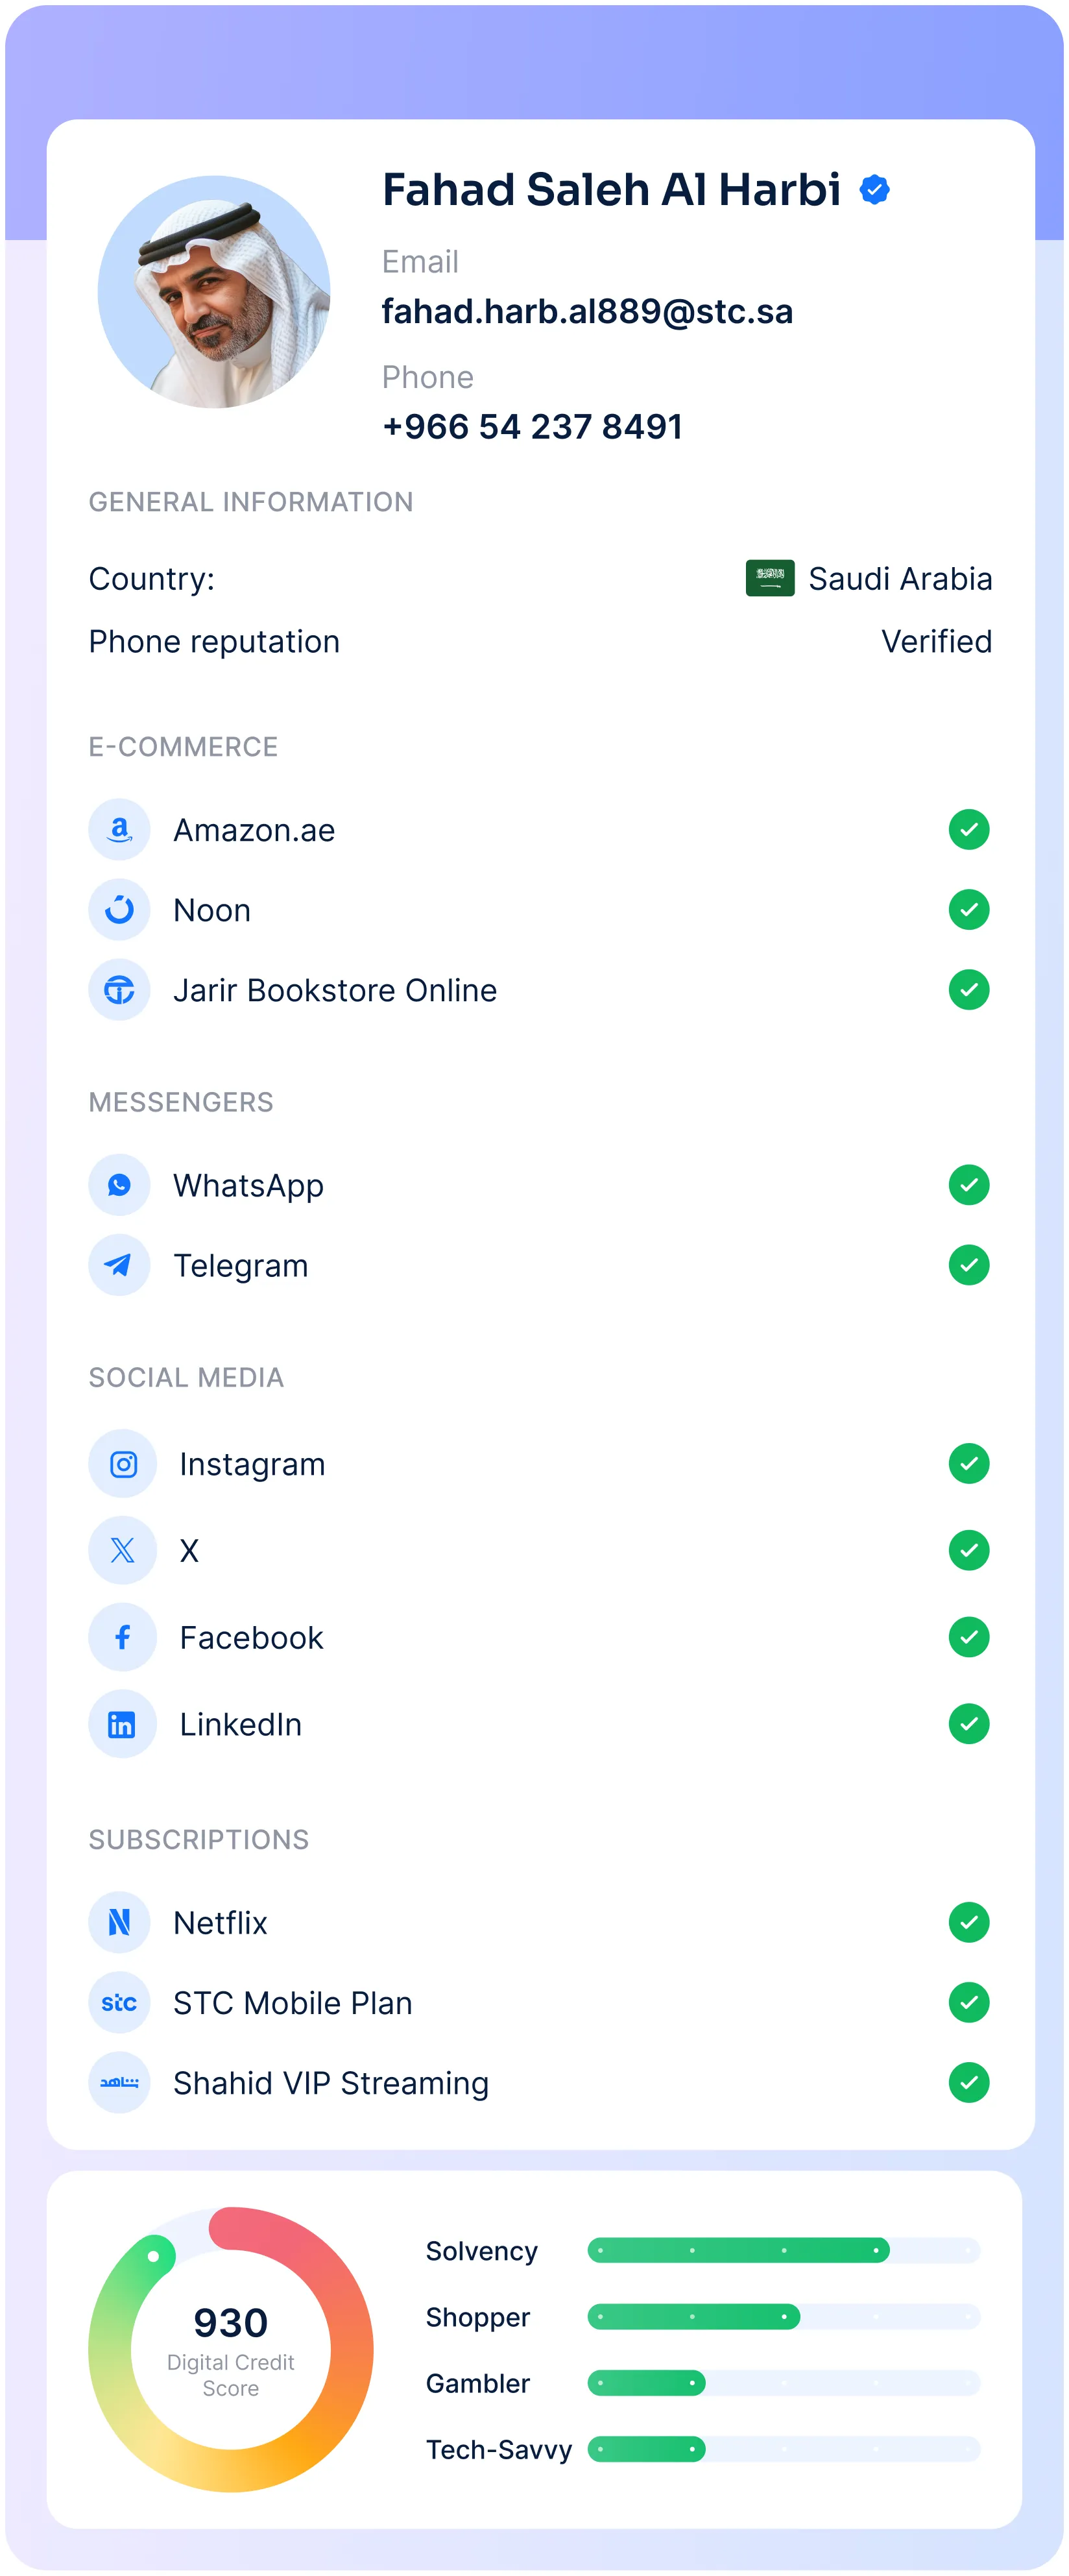
RiskSeal collects data from 200+ online platforms, including Saudi-specific services.
Below is a selection of popular Saudi digital platforms included in our analysis. For the full list, including niche and regional sources, please reach out to our team.

Namshi

Mrsool

Absher
Shahid
How alternative data strengthens lending in Saudi Arabia

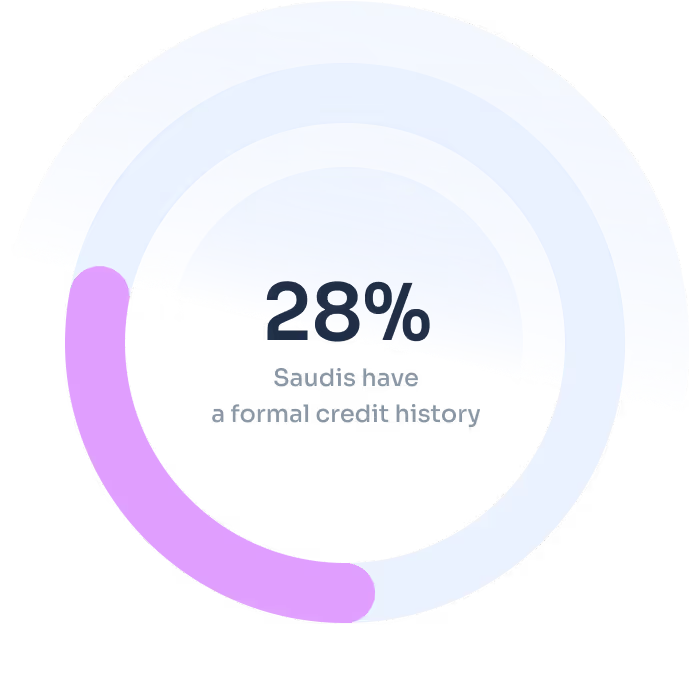
Credit inclusion at scale
Reach the unbanked and underbanked groups with 450+ alternative insights on each borrower.

Grow credit portfolio safely
Approve more borrowers with smarter risk assessments, reduce defaults, and expand lending without slowing business growth.

Real-time, AI-powered scoring
Meet modern borrower expectations with instant credit decisions and seamless onboarding.
Client success stories
See how RiskSeal’s unique data sources generate pure Gini uplift, even in emerging markets. Real numbers. Real before/after performance.




FAQ
What does RiskSeal cost for fintechs in Saudi Arabia?

RiskSeal offers three pricing packages for Saudi Arabian lending providers:
Pilot Program. Designed for fintech startups, pilot projects, and lenders new to alternative data. Pricing starts at $499 per month with a fixed monthly commitment and limited transaction volume. The package includes API integration, basic onboarding and support, and monthly usage reporting.
Enrichment. Intended for banks, digital lenders, and institutions with existing credit models. This package uses usage-based pricing, with clients paying per enriched applicant report. It includes alternative data attributes, risk indicators, flexible integration options, and dedicated implementation and technical support.
Intelligence. Built for large digital lenders, banks launching new digital products, and enterprises transforming their underwriting systems. This package uses custom enterprise pricing and combines RiskSeal’s alternative data with its proprietary scoring model, continuous model optimization, custom decision strategies, and dedicated risk consulting.
RiskSeal also offers a free Proof of Concept (PoC), with no additional fees for integration, support, or training. For more information or to discuss the package best suited to your business, please visit our pricing page or contact our sales team.
What advantages does RiskSeal bring to lenders in Saudi Arabia?
RiskSeal helps Saudi lenders improve credit decisions with:
-Step-by-step onboarding for a smooth start.
-Expert support to understand and apply alternative data.
-24/7 technical assistance whenever you need it.
-99.9% API uptime for reliable access to data.
-A client portal with analytics to track results and optimize your lending.
How can I know if RiskSeal data will benefit my business?
We provide a free Proof of Concept (PoC) for Saudi lenders.
You can test our scoring on your own historical data. This shows how RiskSeal improves risk assessment, helps approve more creditworthy borrowers, and reduces defaults.
After the PoC, we give you a detailed results report. This helps you measure the real value before you decide to integrate our solution fully.
How is alternative data used for credit scoring in Saudi Arabia?
Lenders in Saudi Arabia use alternative data to assess applicants beyond traditional credit bureau records.
This includes digital footprint signals, telecom data, and behavioral patterns that reflect real-world financial activity.
These additional data points help build a more complete risk profile, especially for applicants with limited credit history.
As a result, lenders can make more accurate decisions while expanding access to underserved segments.
Can alternative data help approve more customers in Saudi Arabia?
Yes, alternative data helps lenders identify creditworthy applicants who may not qualify under traditional scoring models.
By analyzing digital behavior and non-bureau signals, lenders can better distinguish between low-risk and high-risk borrowers.
This approach allows fintechs and lenders to safely increase approval rates without compromising risk standards.
It also supports financial inclusion by opening access to credit for thin-file or new-to-credit customers.
What digital tools help streamline underwriting processes?
Modern underwriting relies on digital tools that automate data collection, identity verification, and risk assessment in real time.
These include alternative data platforms like RiskSeal, AI-driven scoring models, and automated decision engines.
By reducing manual checks and accelerating decision-making, these tools help lenders process applications faster and more efficiently.
This leads to lower operational costs and a smoother experience for both teams and customers.