Turn more of your acquired leads into funded loans
RiskSeal adds 450+ real-time digital footprint signals at first contact, helping lenders prioritize stronger prospects, reduce unnecessary data spend, and improve conversion alongside their existing bureau and underwriting processes.

real-time digital signals
online platforms analyzed
to return a digital profile
API uptime
One score band. Many borrower realities.
Traditional bureau data is indispensable, but consumers with similar scores can still differ in current financial pressure, identity confidence, digital stability, and intent to complete a loan.
At the same time, lenders are paying to acquire, verify, and process leads that may never reach funding. The result is a commercial decision that a bureau score alone was not designed to answer:
Which leads justify the next dollar of acquisition, bureau, verification, and servicing spend?
1 in 3
Among US adults who applied for credit in 2025, one-third were denied or approved for less than requested.

$1.26T
US credit-card balances in Q2 2026, within $18.8 trillion of total household debt.

48.1%
Share of consumers with a FICO Score of 750 or higher, even as the national average fell to 714—evidence of a more segmented credit market.
Keep the bureau.
Add a real-time second lens.
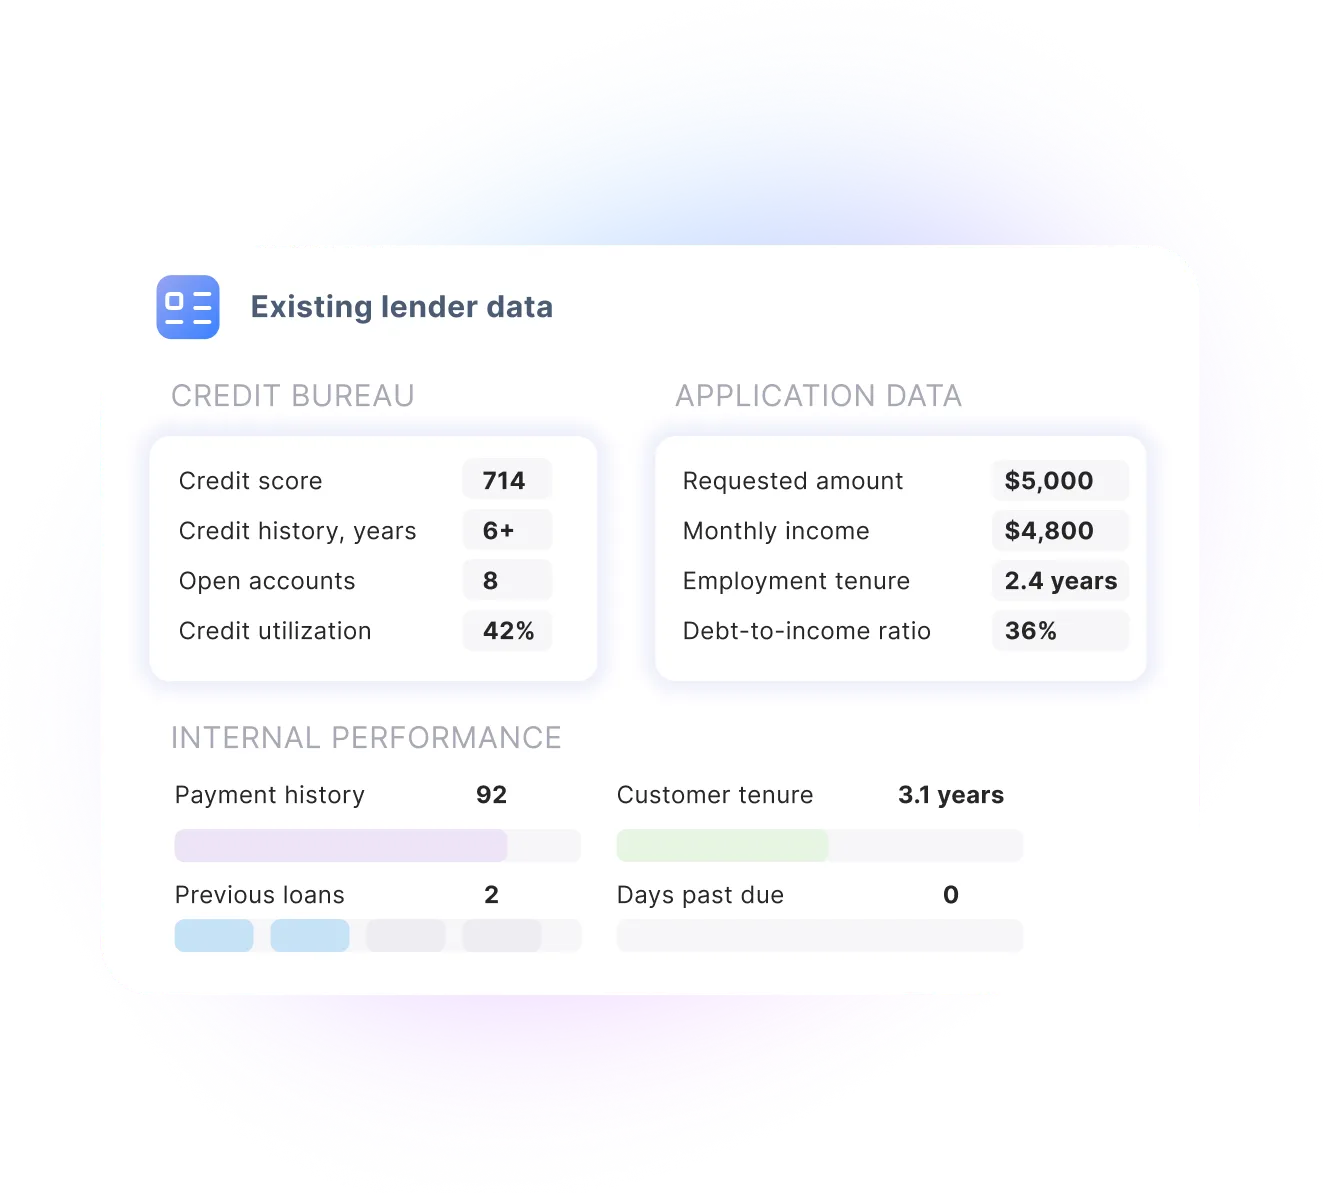
Existing lender data
Start with the information and controls already embedded in your underwriting process.
- Credit bureau history and score
- Application and declared borrower data
- Internal customer and performance records
- Fraud, identity and verification results
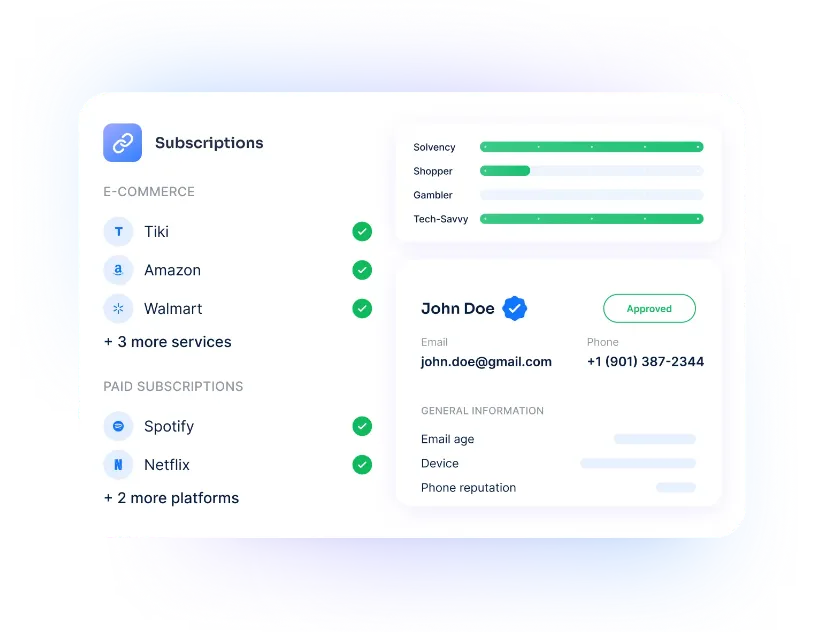
RiskSeal enrichment
Add a real-time view of the applicant’s digital presence without replacing your existing data sources.
- 450+ digital footprint signals
- Coverage across 200+ online services
- Identity, stability and behavioral indicators
- Decision-ready results returned in seconds
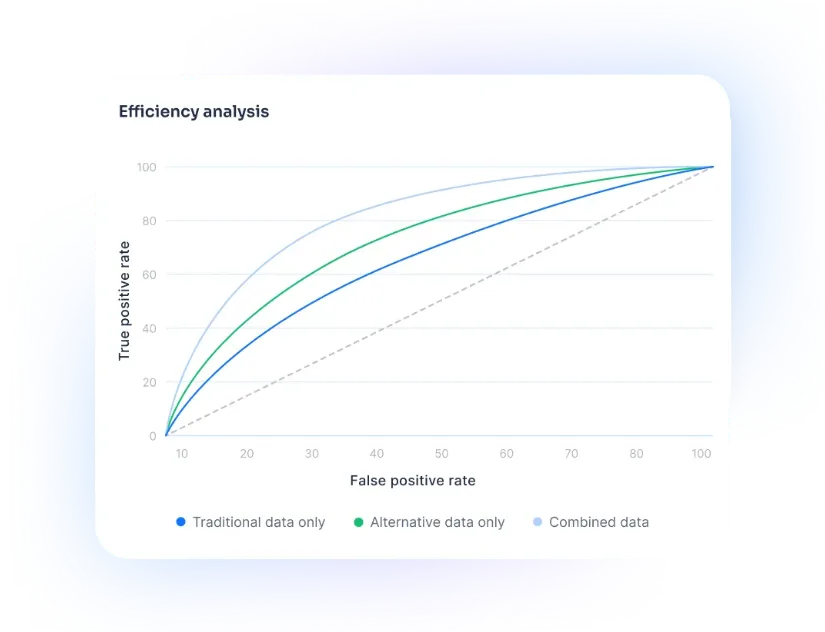
Better segmentation
Combine existing lender data with RiskSeal insights to identify meaningful differences within the same traditional risk band.
- Prioritize leads with stronger progression potential
- Identify applicants less likely to complete the funnel
- Improve differentiation within existing score bands
- Route each applicant through the appropriate lender-defined workflow
Evaluate RiskSeal against your own funnel and funded-loan outcomes before changing production policy
Types of alternative data for credit models
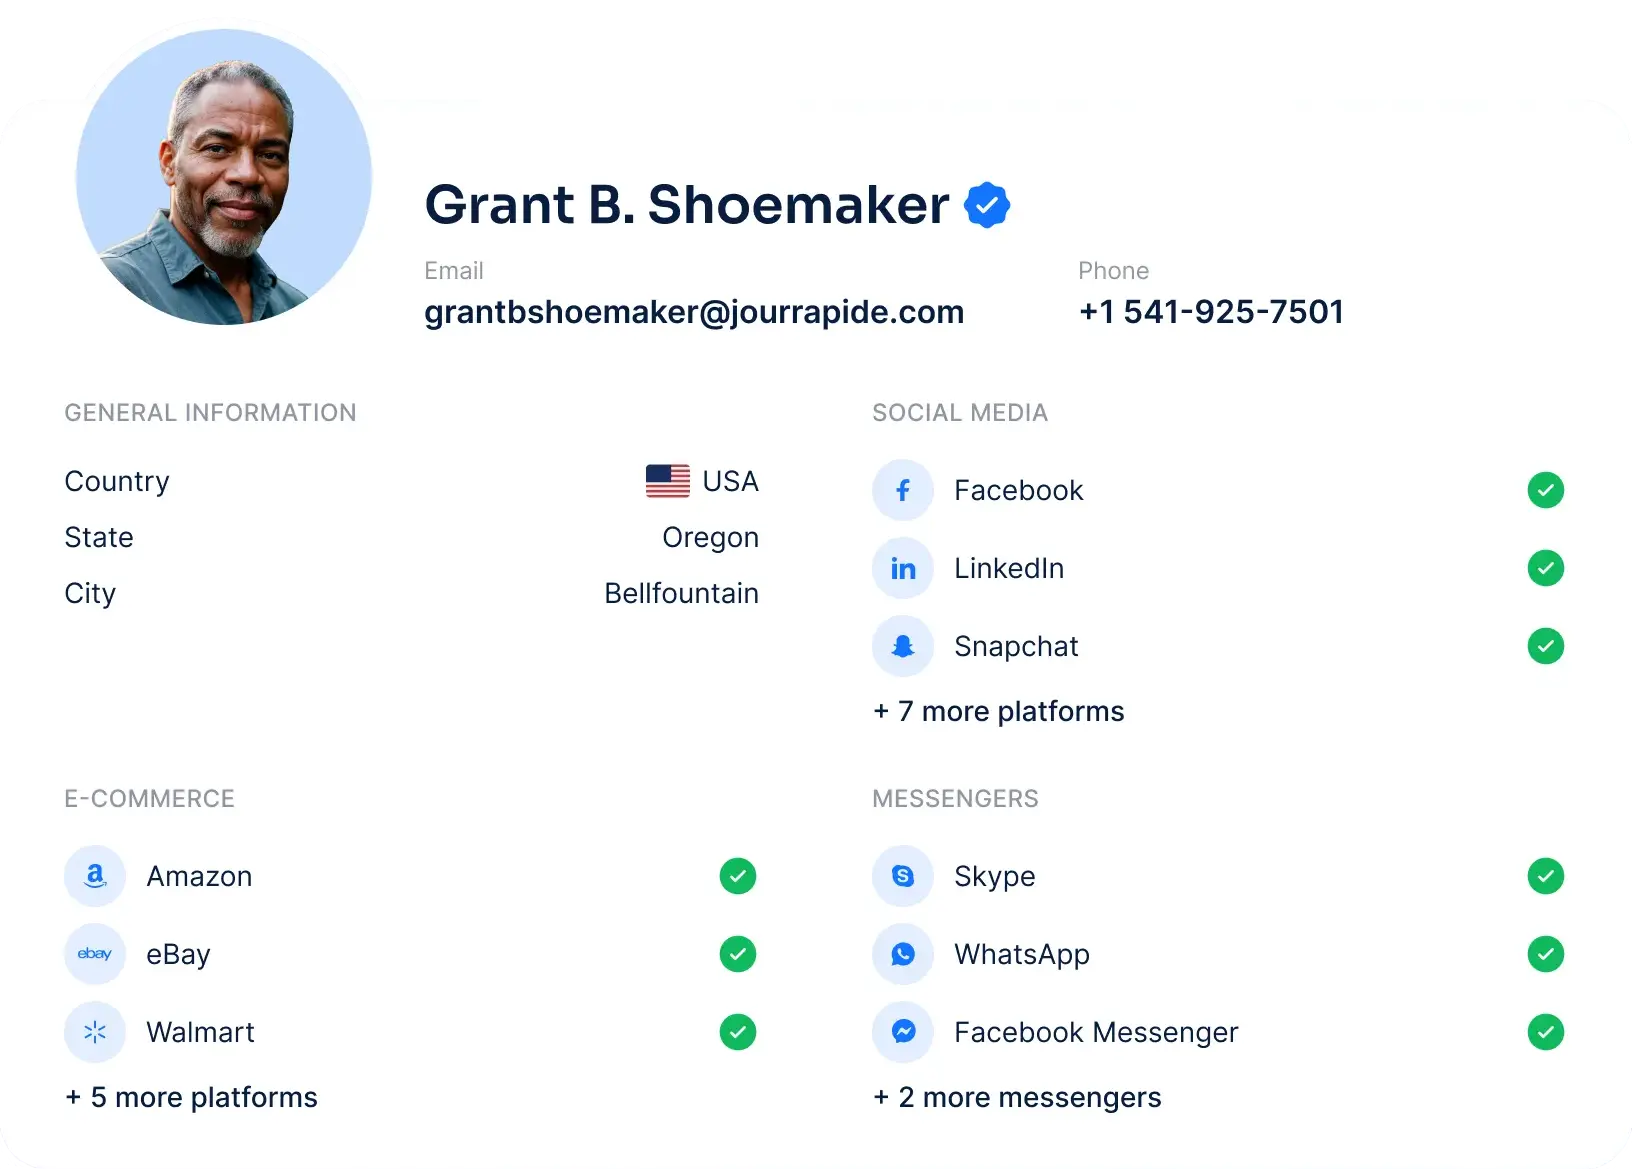
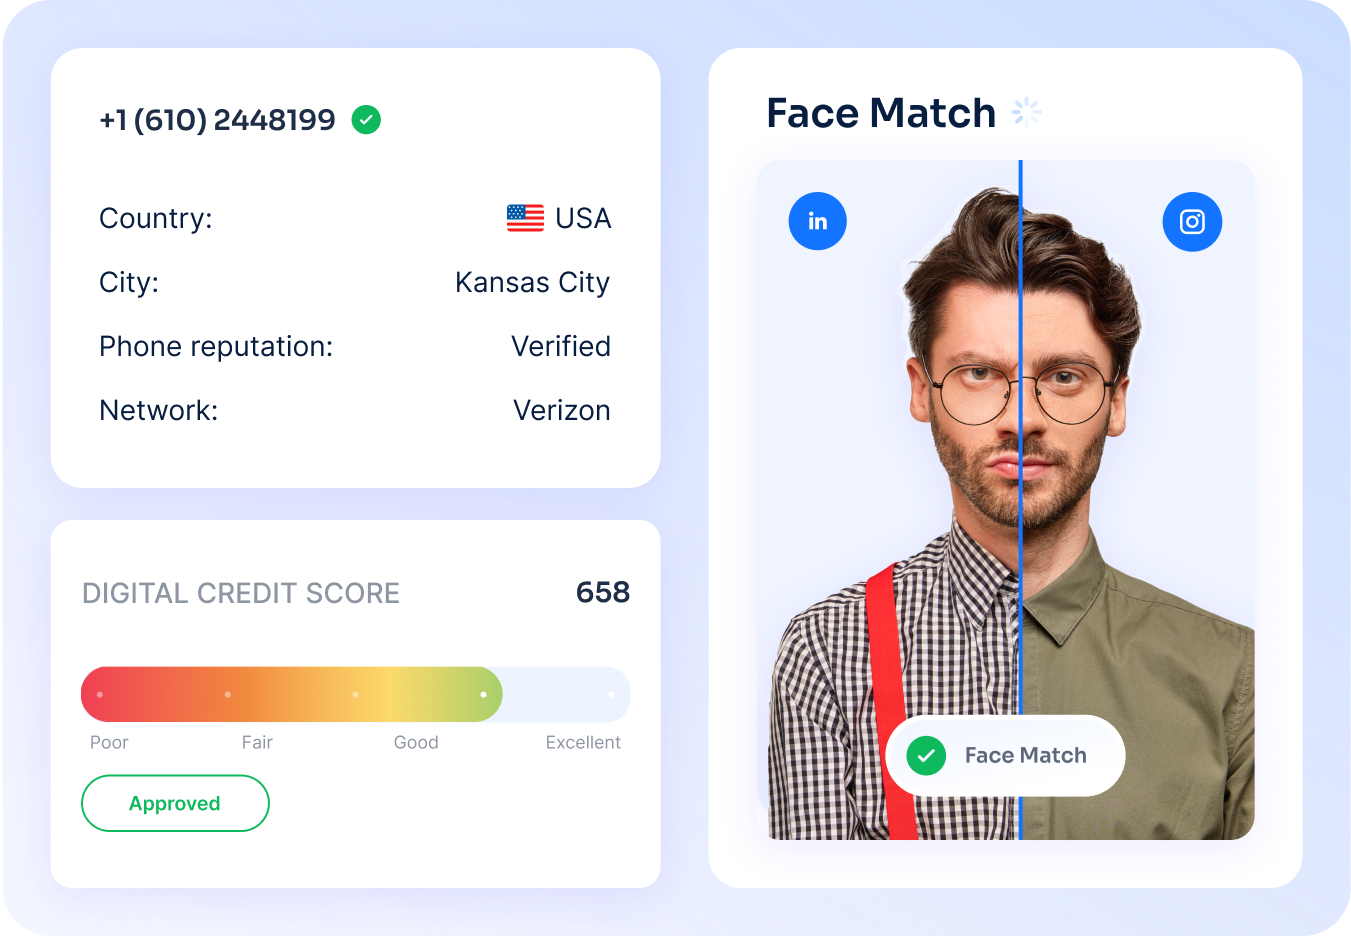
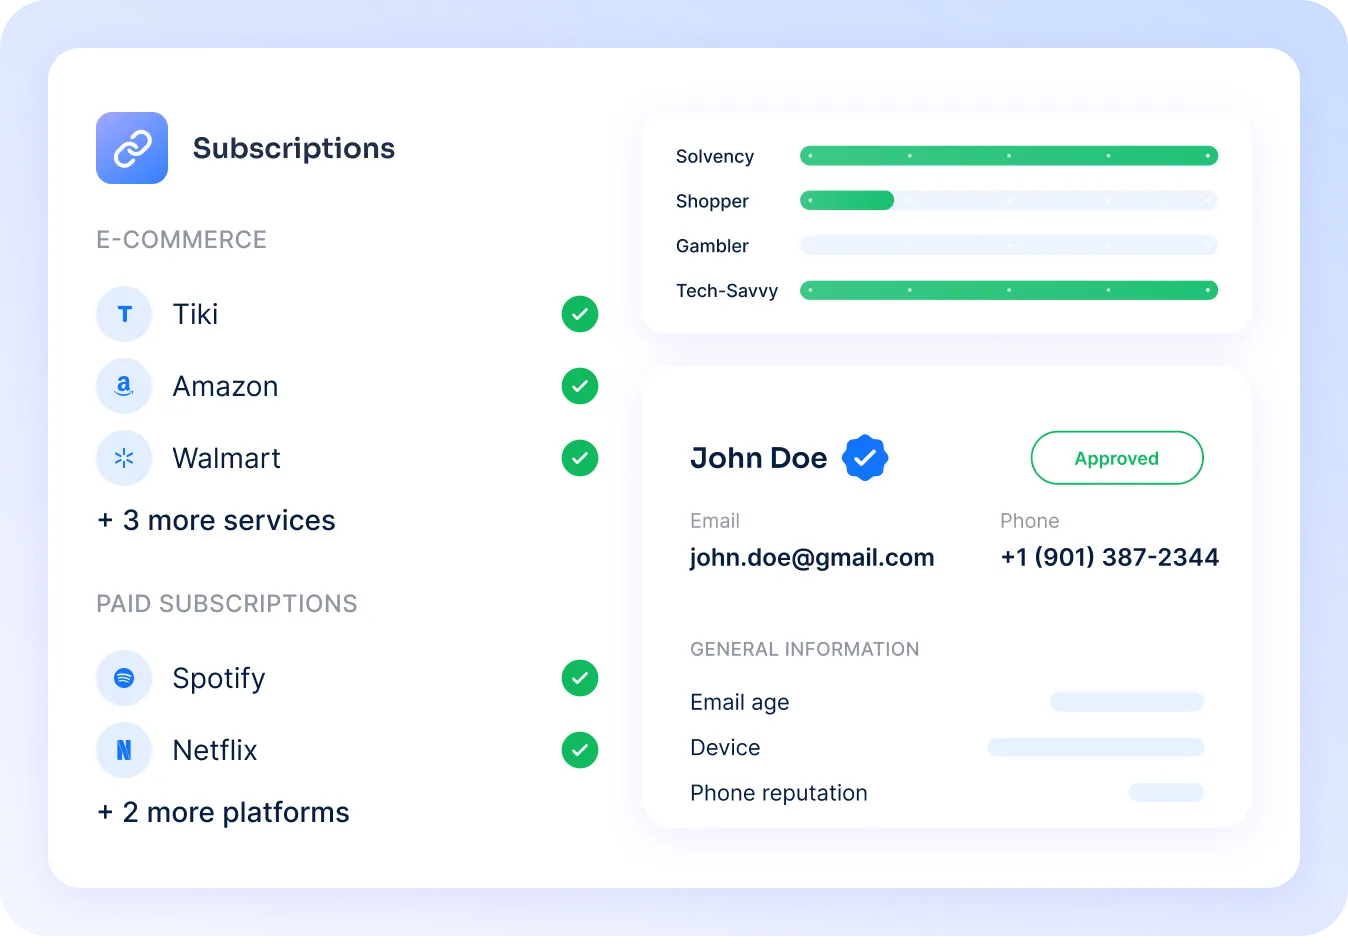
We generate 450+ real-time data points per applicant based on data from 200+ global and local platforms. These signals strengthen models where bureau data is weak or unavailable.
RiskSeal is one of the alternative data companies offering social and behavioral data for credit decisions.
Email intelligence


Phone number intelligence
IP intelligence lookup

E-commerce & subscription signals
Social presence

Improve the economics of every funded loan


Reduce wasted spend
Identify low-progression leads before incurring the full cost of bureau, verification, and manual processing.
Improve conversion
Rank purchased leads by expected completion or funding probability so stronger prospects receive faster follow-up and more appropriate routing.

Differentiate risk
Add real-time signals to help distinguish applicants who look similar in historical credit data.

Expand responsible opportunity
Create a measurable second-look path for thin-file or borderline applicants, subject to lender policy and compliance review.
Regional United States services used for digital footprint analysis
RiskSeal analyzes applicants’ digital footprints across 200+ online services and social media platforms, including many of the world’s leading platforms. We also provide US lenders with alternative data from relevant local and regional services.
Contact our team to explore the full list of available data sources, including specialized and niche platforms.

Amazon

Ebay

Doordash

Bestbuy

Walmart

Disney+


Zoho

Spotify
One early signal. Two immediate use cases.
Reduce avoidable data spend
RiskSeal evaluates a lead at first contact, before the lender runs its full data stack.
Possible actions
Improve conversion
Use estimated funding probability to focus service capacity where it can influence the outcome.
Possible applications
Client success stories
See how RiskSeal’s unique data sources generate pure Gini uplift, even in emerging markets. Real numbers. Real before/after performance.




FAQ
How much does your solution cost for US fintech providers?

RiskSeal offers three pricing packages for USA lending providers:
Pilot Program. Designed for fintech startups, pilot projects, and lenders new to alternative data. Pricing starts at $499 per month with a fixed monthly commitment and limited transaction volume. The package includes API integration, basic onboarding and support, and monthly usage reporting.
Enrichment. Intended for banks, digital lenders, and institutions with existing credit models. This package uses usage-based pricing, with clients paying per enriched applicant report. It includes alternative data attributes, risk indicators, flexible integration options, and dedicated implementation and technical support.
Intelligence. Built for large digital lenders, banks launching new digital products, and enterprises transforming their underwriting systems. This package uses custom enterprise pricing and combines RiskSeal’s alternative data with its proprietary scoring model, continuous model optimization, custom decision strategies, and dedicated risk consulting.
RiskSeal also offers a free Proof of Concept (PoC), with no additional fees for integration, support, or training. For more information or to discuss the package best suited to your business, please visit our pricing page pricing page or contact our sales team.
What added value does RiskSeal provide to its customers in the USA?
RiskSeal delivers substantial benefits to its clients in the USA, including:
Personalized onboarding guidance. Clients receive hands-on assistance during the setup process.
Expert support in data interpretation. We help you understand and leverage the data effectively.
24/7 technical support. Our team is available to resolve any technical issues, ensuring minimal downtime.
99.9% uptime guarantee for APIs. RiskSeal commits to high reliability, which is crucial for financial operations.
Unlimited access to a client portal with detailed analytics. Actionable analytics to monitor performance and optimize operations.
How can I make sure RiskSeal’s data works for my company?
To ensure RiskSeal data works for your company, you can use a free Proof of Concept (PoC) against your historical transactions.
This enables you to directly assess the value of RiskSeal's digital credit scoring solution in the context of your data and estimate a potential uplift for your scoring models.
After the PoC, we provide you with an analysis of historical transactions, demonstrating how RiskSeal can enhance your existing scoring models. This approach ensures you can make an informed decision about integrating RiskSeal's solutions into your business framework.
Is alternative data allowed for credit scoring in the USA?
Yes, alternative data is permitted for credit scoring in the US, provided it is used within the bounds of federal law.
The two primary frameworks are the Fair Credit Reporting Act (FCRA) and the Equal Credit Opportunity Act (ECOA). Lenders must ensure alternative data doesn't act as a proxy for protected characteristics like race or gender, and that proper adverse action disclosures are made.
RiskSeal uses only publicly accessible digital signals or data collected with explicit user consent making it straightforward for US lenders to adopt alternative scoring compliantly.
How does RiskSeal help fintech companies stay compliant with US regulations?
RiskSeal is built with compliance as a core design principle.
It processes only public digital signals or consented data. No private messages or accounts accessed.
All data is encrypted, stored in ISO 27001-certified infrastructure, and never sold to third parties. Scoring is based on financial and behavioral indicators rather than demographic proxies, reducing fair lending risk under ECOA.
RiskSeal also supports real-time watchlist screening against global sanctions lists and PEP databases for AML compliance.
Can alternative data improve approval rates for thin-file borrowers in the US?
Yes, this is one of the most impactful use cases for alternative data.
19% of the US population is unscorable by traditional bureaus. But a thin credit file doesn't mean a person is a risky borrower. It often just means they're new to credit, recently immigrated, or simply prefer cash and debit.
These individuals can still have a rich digital footprint that signals financial responsibility: stable online presence, consistent account history across platforms, responsible spending patterns, and verified identity signals.
RiskSeal analyzes over 450 such data points – derived from just an email, phone number, and IP address – to build a comprehensive risk profile in under five seconds.
This gives lenders a meaningful, evidence-based way to say "yes" to creditworthy borrowers they would otherwise have to turn away.